
Finance your dream build.
Construction loans tailored to support every stage of your build.
Building Your FutureBuilding starts with the right loan.
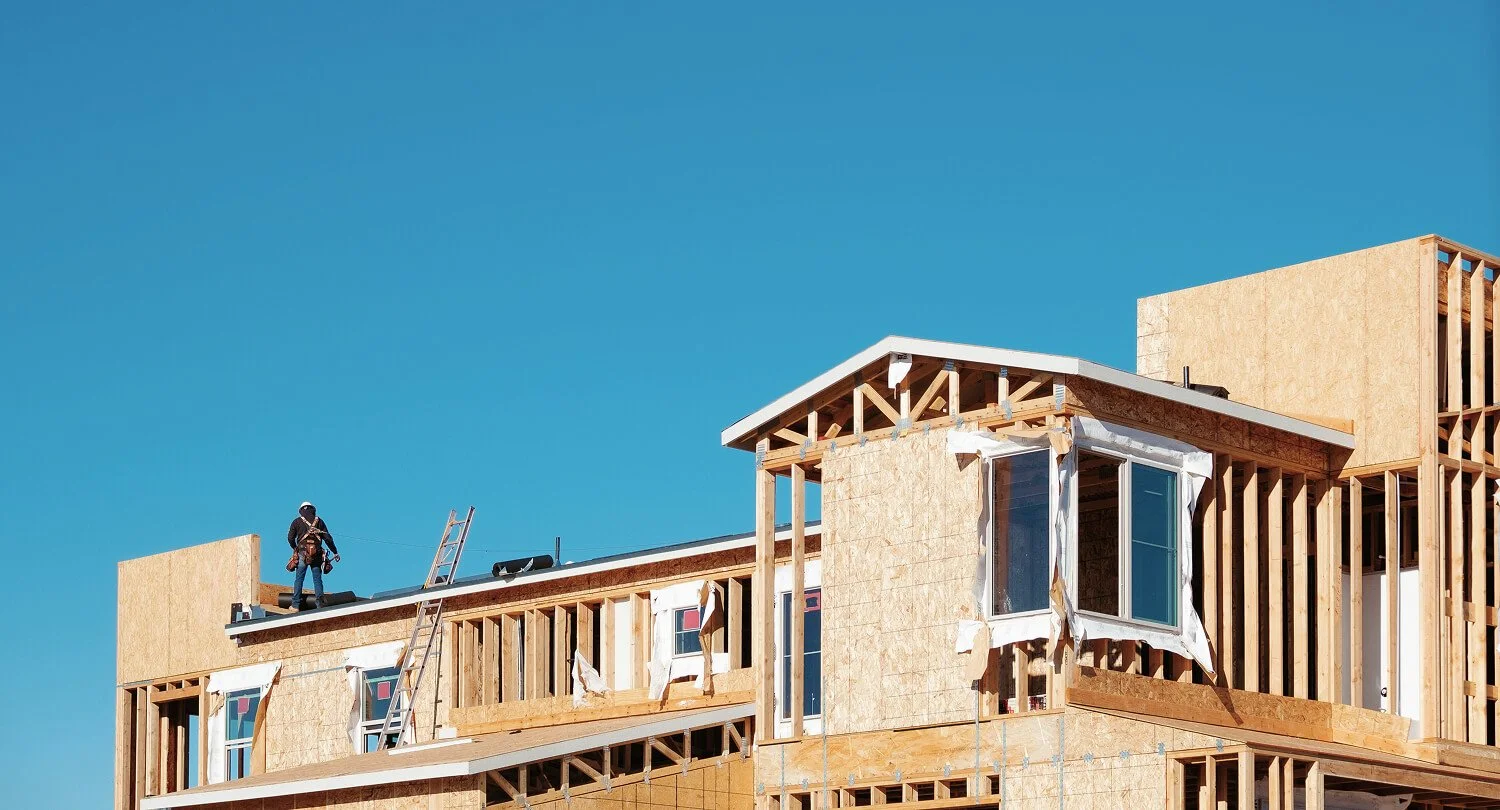
A construction loan is designed to help finance the building of a new home, with funds released in stages as construction progresses. Unlike a standard home loan, it provides funding throughout the build, helping you manage costs from the foundation through to completion.
Whether you're building your first home, upgrading to your forever home, or constructing an investment property, the right construction loan should align with your budget, timeline, and building plans. Choosing the right finance can help keep your project on track from start to finish.
At Spitfire Finance, we take the time to understand your project before comparing suitable construction loan options from our panel of trusted lenders. We'll explain the process clearly, work alongside you throughout the build, and help you move forward with confidence.
Built for Your ProjectFeatures designed for your build.
-
Progressive Stage Payments
Funds are released in stages throughout the construction process, helping keep your build moving from foundation to completion.
-
Interest-Only During Construction
Many construction loans allow you to pay interest only on the funds drawn down while your home is being built, helping manage your cash flow.
-
Flexible Loan Options
Choose from a range of loan structures and repayment options to suit your project and financial goals.
-
Finance for Owner-Occupiers & Investors
Whether you're building your dream home or an investment property, we'll help you find the right lending solution.
-
Access to 60+ Lenders
Compare construction loan options from a broad panel of trusted lenders, giving you greater choice and competitive solutions.
-
Expert Guidance Throughout Your Build
From pre-approval through to the final progress payment, we'll guide you through each stage of the construction loan process.
A Simple Path to the Right Home Loan
Let’s Chat
Tell us about your goals and financial situation.
We Compare
We assess loan options from our panel of trusted lenders.
You Choose
We explain your options so you can make an informed decision.
Settled
We manage the paperwork and keep everything on track through to settlement.
Our CommitmentMore Choice. Less Stress. Better Outcomes.
-
Access to 60+ Lenders
We compare home loan options from more than 60 trusted lenders, giving you greater choice and helping you find the right fit.
-
Rated 5.0 by Clients
Our reputation is built on honest advice, responsive service, and helping clients achieve their property goals with confidence.
-
All You Need Is One Person
You'll work with one dedicated broker from your first conversation through to settlement, with clear guidance every step of the way.
-
No Cost (Paid by the Lender)
Our mortgage broking service comes at no cost to you, so you can access expert advice without paying broker fees.
Frequently Asked Questions
-
Your construction loan is released in stages — typically slab, frame, lock-up, fixing, and completion — and your lender pays your builder directly after each stage is completed and (usually) inspected. You’re not handing money to your builder yourself; the lender manages this against your fixed-price building contract. This protects you from paying for work that hasn’t been done, but it also means delays in one stage can hold up the next payment, so it’s worth understanding the schedule upfront.
-
Building costs can shift between signing your contract and completion, particularly with provisional sum and prime cost (PC) items, which are often estimates rather than fixed prices. If costs increase, you may need to fund the difference yourself or, in some cases, increase your loan (subject to a new approval and valuation). Delays can also affect a construction loan’s approval expiry or any fixed-rate period attached to your loan. Budgeting a contingency buffer, and understanding what’s genuinely fixed in your contract versus estimated, is one of the most valuable conversations to have before you sign.
-
Most lenders want to see council-approved plans (or at least a development application well progressed) before formally approving your loan, alongside a signed fixed-price building contract with a licensed builder. Preapproval can sometimes be arranged earlier in the process to give you a budget to work with, but full loan approval typically waits until your plans and contract are finalised.
-
Yes. Land and construction is usually structured as a single facility with two phases: the land component is drawn at settlement, and the construction component is drawn progressively as the build proceeds, with interest generally charged only on the funds drawn so far. This is different from a standard purchase, where you draw the full loan amount upfront. Getting the timing right between land settlement and the start of construction can also matter for grant and duty eligibility, so it’s worth planning this sequence with us early.
Still Have a Question?
If your question isn’t answered here, that’s exactly what we’re here for. Every situation is different, and general information can only take you so far.
Get Started and let’s talk through your specific circumstances.
What Our Clients Say